Key takeaways
- Borrowing to consume only makes sense when the benefit of having something today outweighs the interest cost.
- Interest works like rent: it is the fee for using money you have not earned yet, before you have earned it.
- The benefit of getting something early takes one of three forms: income that starts sooner, a larger expense avoided, or a critical need that cannot wait.
- With high rates, the benefit of buying early must be very large: a purchase that makes sense at 1% per month may stop making sense at 3%.
- The cost of a debt lies in the gap between the cash price and the total paid, not in the monthly installment.
A course that costs USD 1,000 and is bought on credit ends up costing USD 1,100.
Those USD 100 of difference pay for one thing only: starting six months earlier. Whoever signs the loan is buying time, and time has a price that almost nobody calculates before paying.
Borrowing to consume only makes sense when the benefit of having something today outweighs the cost of the interest. This text defends that sentence and shows how to apply it to any purchase.
Every loan pulls the calendar forward
A person without debt buys at the pace of their savings. If an item costs six months of surplus, they have it in month six.
Credit breaks that sequence. The bank hands over today the money the person would have gathered six months from now, and charges for that advance.
A useful way to see the mechanism is to think of interest as rent. The borrower uses money they have not yet earned, and interest is the rent for using it early. The rent grows with two variables: the rate and the time the money stays borrowed.
This logic removes the moral judgment from the equation. Nobody needs to decide whether debt is good or bad in the abstract. The real decision is knowing whether the advance is worth what it costs.
In most cases that question has a numerical answer. And when it does not, that absence also tells us something...
The scale has two pans, and both can be measured
One pan holds the financial cost, the difference between the cash price and the total paid. That number comes from a subtraction and appears in any credit offer that states the total amount to be paid.
The other pan holds the benefit of getting it early: what is gained or avoided by having it sooner. This second number takes more work.
The benefit of getting something early usually takes one of these three forms:
- Income that starts sooner. A work tool produces from the first month, instead of from month six.
- A larger expense avoided. A postponed repair can worsen and cost more than the interest on the loan that would have fixed it on time.
- A critical need for well-being that cannot wait. Some health or housing needs lose their meaning if they are addressed months later.
When the item fits none of the three, the benefit pan is empty. The interest then buys only the satisfaction of not waiting.
Paying interest just to avoid waiting is the most expensive use a loan can have. The desire to have something is already legitimate, but it carries no weight on the scale.
The same interest weighs differently depending on what it finances
The rate measures how much money costs. The useful life of the item measures how long what the money bought lasts. When those two durations fall out of step, the debt outlives the benefit.
A dinner financed in 12 installments illustrates the mismatch. The dinner lasts one night and the installments last a year. For eleven months, the person pays for something that no longer exists.
A home shows the opposite case. A mortgage brings forward an asset that the person would take, for example, 15 years to save for. Throughout that term, the home keeps providing the service for which the installments are paid.
The rate adds a second layer. The class Qué debo (What I Owe) of the program compares one million borrowed at 1% per month with the same million at 3% per month. At 1%, the first month's interest totals $10,000. At 3%, it totals $30,000.
Compounded over twelve months, those rates are roughly equivalent to 12.7% and 42.6% per year. It is the same purchase and the same term, with a rent three times larger.
With high rates, the benefit of getting something early must be very large for the scale to tip toward credit. A purchase that makes sense at 1% per month may stop making sense at 3%.
The USD 1,000 course, figure by figure
The course example lets us see the full scale with concrete numbers.
The first route is to wait. The person saves for six months, pays USD 1,000 in cash and starts studying in month seven. Their financial cost is zero.
The second route is to borrow. The person starts today, pays USD 1,100 in total and their financial cost is USD 100, equivalent to 10% of the cash price.
The decisive question is what those six months of advantage produce. To cover USD 100 of interest over a six-month period, the course would have to generate on average about USD 16.7 per month, in additional income or avoided expenses.
If the course enables a better-paid job, a new client or a task that is currently outsourced, that figure may be achievable. In that scenario, waiting also has a cost: six months without applying what was learned.
If the person plans to use the course within a year, the calculation changes completely. Bringing the purchase forward six months generates nothing, and the USD 100 leaves the pocket with nothing in return.
It is the same course, at the same price and with the same loan. The scale tips to opposite sides depending on how the advance is used.
Two errors that throw off the scale
The first error is looking at the installment instead of the total. The monthly installment measures how much money leaves each month and affects cash flow. The cost of the debt, by contrast, lies in the difference between the cash price and the total.
A small installment can hide a high financial cost when the term stretches. Someone who compares offers only by installment often chooses the most expensive one.
The second error is putting the desire on the benefit pan. The phrase “I need it now” often describes an urgency that disappears within a few weeks.
The benefit that counts has a name and a number: a concrete income, an avoided expense or a need that cannot wait. If the person cannot write it in one line, treat it as zero.
This second error has a cumulative effect. Each consumer purchase financed without a measurable benefit adds installments that shrink the margin for the next decision.
What to check before signing
Any reader can apply this test to a real credit offer, without special tools:
- Find the cash price and the total to pay in the offer, and subtract them. The result is the financial cost.
- Divide that cost by the number of months the loan brings the purchase forward. The result is the monthly price of the advance.
- Write what the item produces or avoids in each of those months, with a figure or a concrete fact.
If the third step is left empty, the scale already has its answer.
The test is falsifiable and can be reviewed later. If, at the end of the term, the item did not generate the expected income or avoid the expected expense, the record shows it. That evidence improves the next decision.
Waiting is also a decision
Whoever waits saves the financial cost and gives up the months of use. Whoever borrows against a measurable benefit pays interest in exchange for productive time.
Both routes can be correct. The mistake lies in signing without having weighed both pans.
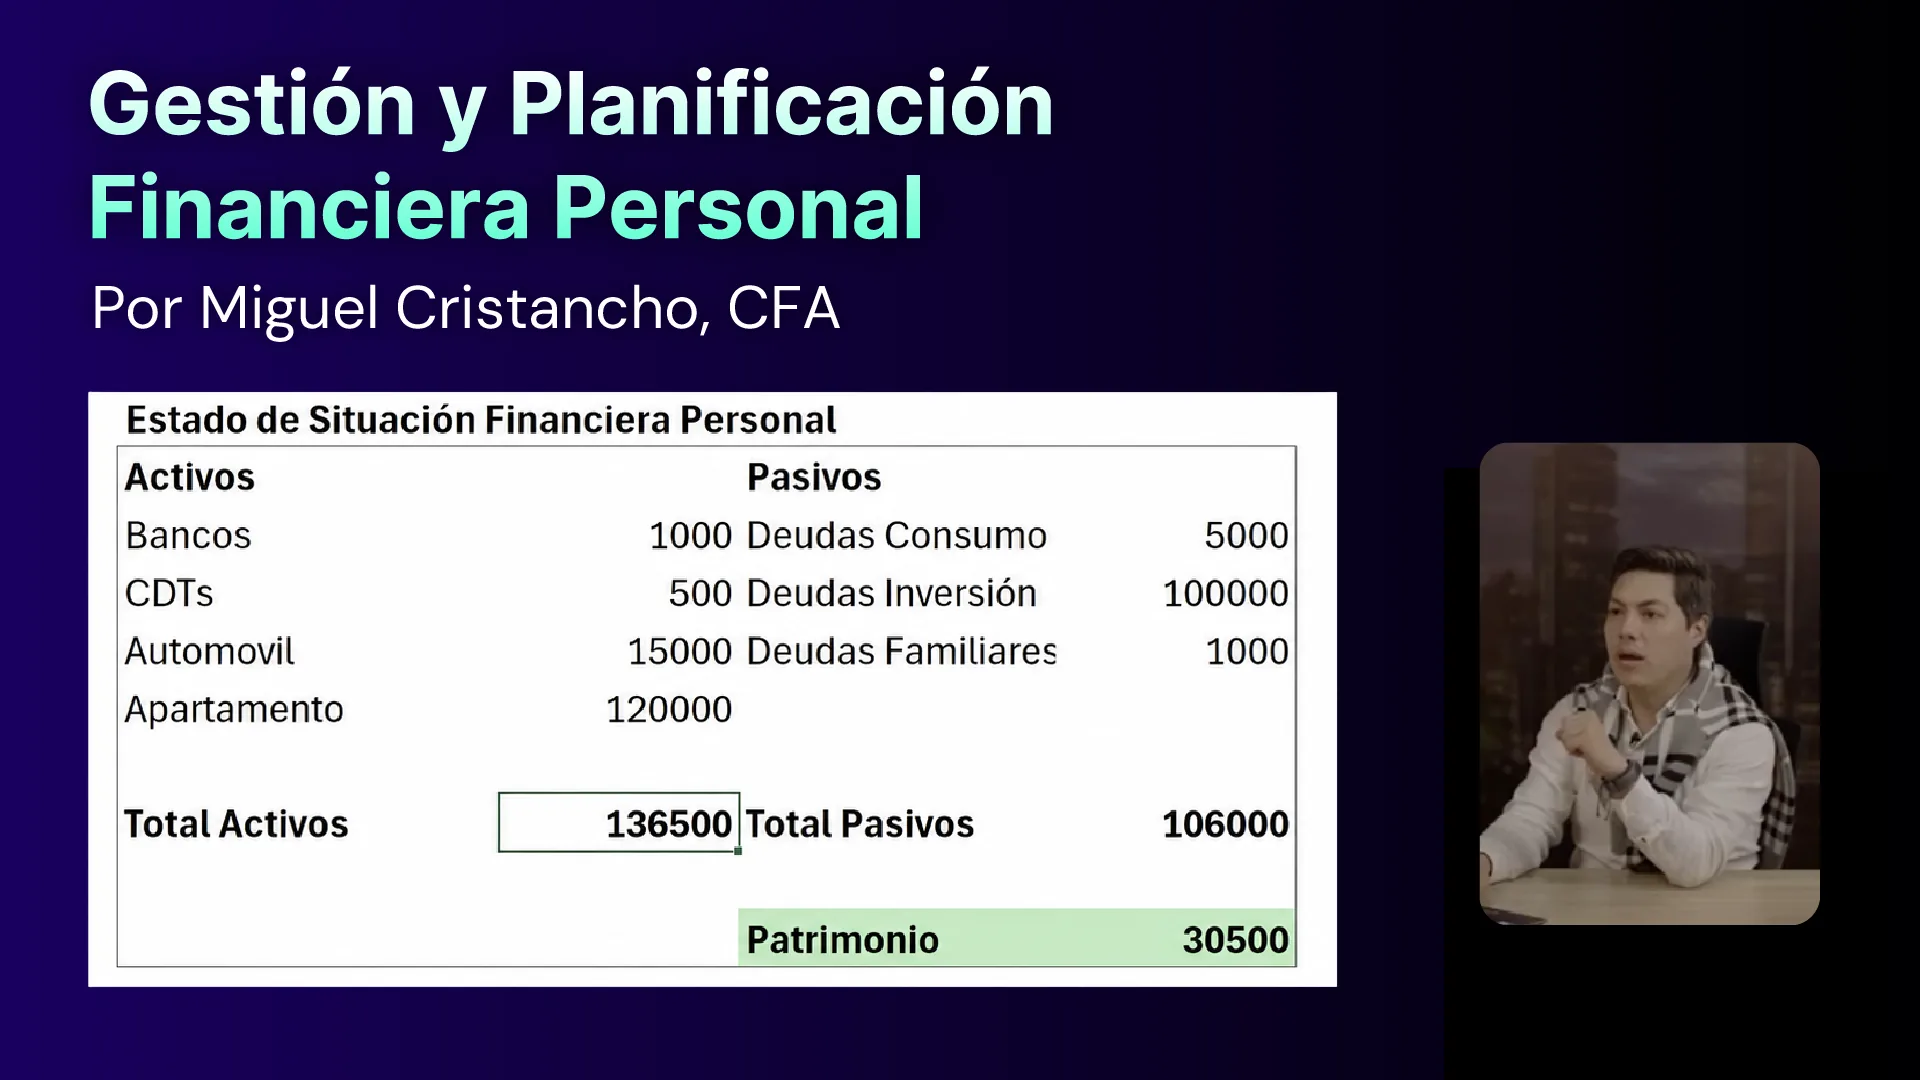
The class ¿Endeudarme o esperar? (Borrow or Wait), from module 3 of Cronoss's program Gestión y Planificación Financiera Personal (Personal Financial Management and Planning), works through this exercise with the program's borrowing tool. It takes a specific purchase and compares its cost with and without credit.
Here is all the information about the program Gestión y Planificación Financiera Personal.
Educational content. Cronoss is not a broker, investment firm or financial adviser, and nothing above is an investment recommendation.
Frequently asked questions
When does it make sense to borrow to buy something?
When the benefit of having it today outweighs the interest cost. That benefit must have a name and a number: income that starts sooner, a larger expense avoided, or a need that cannot wait. If it cannot be written in one line, treat it as zero.
How do I calculate the real cost of a loan?
Subtract the cash price from the total to be paid. That result is the financial cost. Then divide it by the number of months the loan brings the purchase forward to get the monthly price of getting it early.
Why is comparing the monthly installment not enough?
The installment measures how much money leaves each month, not how much the debt costs. A small installment can hide a high financial cost when the term stretches, so someone who compares only by installment often picks the most expensive offer.
What if I finance something that lasts less than the loan?
The debt outlasts the benefit. A dinner financed in 12 installments lasts one night but is paid for over a year, while a home keeps providing its service for the entire term of the mortgage.