Key takeaways
- Sector rotation compares which sectors gain or lose strength against the market, not which sector is good in absolute terms.
- Relative strength divides a sector's price by a reference index's price, and it should be read across several time windows.
- Relative volume confirms a move when current volume stays above its average over time, not when it spikes on a single day.
- ADX measures trend strength but not direction, and it is a lagging indicator that does not work as a fixed rule.
- No rotation indicator guarantees an outcome, so define in advance which reading would invalidate your thesis before changing a portfolio.
When a market rises, it almost never rises everywhere at once. Some sectors move ahead strongly while others lag or fall, and that gap often says more than the broad index. Sector rotation is the practice of following those shifts in leadership to understand where the money is moving.
This method starts from an old principle: volume and trend strength help read the market better than price alone. Here we turn that into a written method, with its tools and its limits.
Rotating is not guessing the next winning sector. It is measuring which groups gain strength, confirming with volume, and deciding with clear rules.
What sector rotation is
The economy is divided into sectors, such as technology, health care, energy, consumer goods, financials or utilities. Each one groups companies that respond to similar factors: interest rates, raw material prices, household demand or regulation. Sector rotation looks at how capital moves from some sectors to others over time.
The idea is not that a sector is good or bad in the abstract. What matters is its relative position, meaning whether it gains or loses strength against the market as a whole. A sector can rise and still be the laggard if the index rises more. That is why the reading is made in comparison, not in absolute terms.
This view also avoids a common mistake: confusing a sector that rises with a sector that leads. When the whole market rises, many sectors rise. The one that really leads is the one that rises more than the rest.
Relative strength: comparing against the market
The basic tool is relative strength. You divide the price of a sector by the price of a reference index and watch whether that ratio rises or falls. If it rises, the sector is beating the market in that period. If it falls, it is trailing.
It helps to read the line over several windows, for example a few weeks, a few months and a year. A sector that improves across all three shows a more consistent signal than one that only bounces for a day. The method measures relative movement: it does not explain why that movement happens. That part requires economic data and the context of each period.
In practice, the line is built from the closing values of each period. If the ratio rises for several weeks in a row, the reading gains consistency. If it rises for one day and then falls back, it is most likely noise. That difference is easier to see on a chart than in a single figure, so review the whole line before drawing conclusions.
Volume as confirmation
Charles Dow left a principle that sums up in one phrase: volume is what confirms. A rise with growing volume suggests participants are willing to buy at those prices. A rise on thin volume can be a weak move that reverses soon.
The logic is simple. Price tells you what happened, and volume shows how much trading backs it up. Volume can also be misread, because large orders are usually split into many small trades. That is why it helps to look at volume as a process over several weeks rather than as a single day. Two questions are useful here: did volume rise with the move, and did it stay elevated after the first session? Both answers tell you more than one high number.
Relative volume: a worked example
Relative volume compares today's volume with the average volume of a prior period. This is an arithmetic example with figures of our own, only to illustrate the calculation:
Relative volume = today's volume / average volume over the last 20 sessions
Suppose a sector averages 1,200,000 shares a day over the last 20 sessions and today it trades 2,640,000. The calculation is 2,640,000 / 1,200,000 = 2.2. Today's volume is 2.2 times the average.
The next day volume is 900,000. The calculation is 900,000 / 1,200,000 = 0.75. It sits below the average, so it does not confirm the previous day's move.
This example shows the arithmetic, not a signal. The more-than-double threshold some analysts use is a working convention that each reader should test on their own data before using it.
Trend strength: what ADX measures
The ADX (Average Directional Index) measures how strong a trend is, but it does not indicate whether the trend is rising or falling. That difference matters: a high reading can belong to a decline as strong as a rise.
It is used as a complement to volume. When a trend gains strength, readings tend to rise; when it runs out of steam, they tend to flatten or fall. It also helps to know that smoothing and the number of periods change how sensitive the indicator is, and that shorter periods help you see earlier when momentum fades.
A practical way to use it is to watch whether the reading changes slope while price keeps advancing. That divergence is not a sell order, but it is a question worth answering before you increase exposure to that sector.
Its limits are clear. ADX is calculated from price, so it is a lagging indicator, and there is no universal threshold that turns it into a rule. The numeric cut-offs that circulate among analysts have not been checked against an external source for this article, so test them before using them as criteria.
The business cycle: why the order matters
A business reading suggests that sectors react differently depending on the economic phase. Sectors more sensitive to growth, such as those tied to discretionary consumption or industrial investment, tend to carry more weight when activity accelerates. Sectors with steadier demand, such as food or utilities, are often described as defensive when the economy slows.
This is a working hypothesis, not a rule. There are cycles where the order changes, and interest rates, inflation or a supply shock can alter the sequence. That is why the cycle is most useful for framing questions: if the economy slows, does the leading sector still behave as defensive? And does volume confirm it?
What to check before changing the portfolio structure
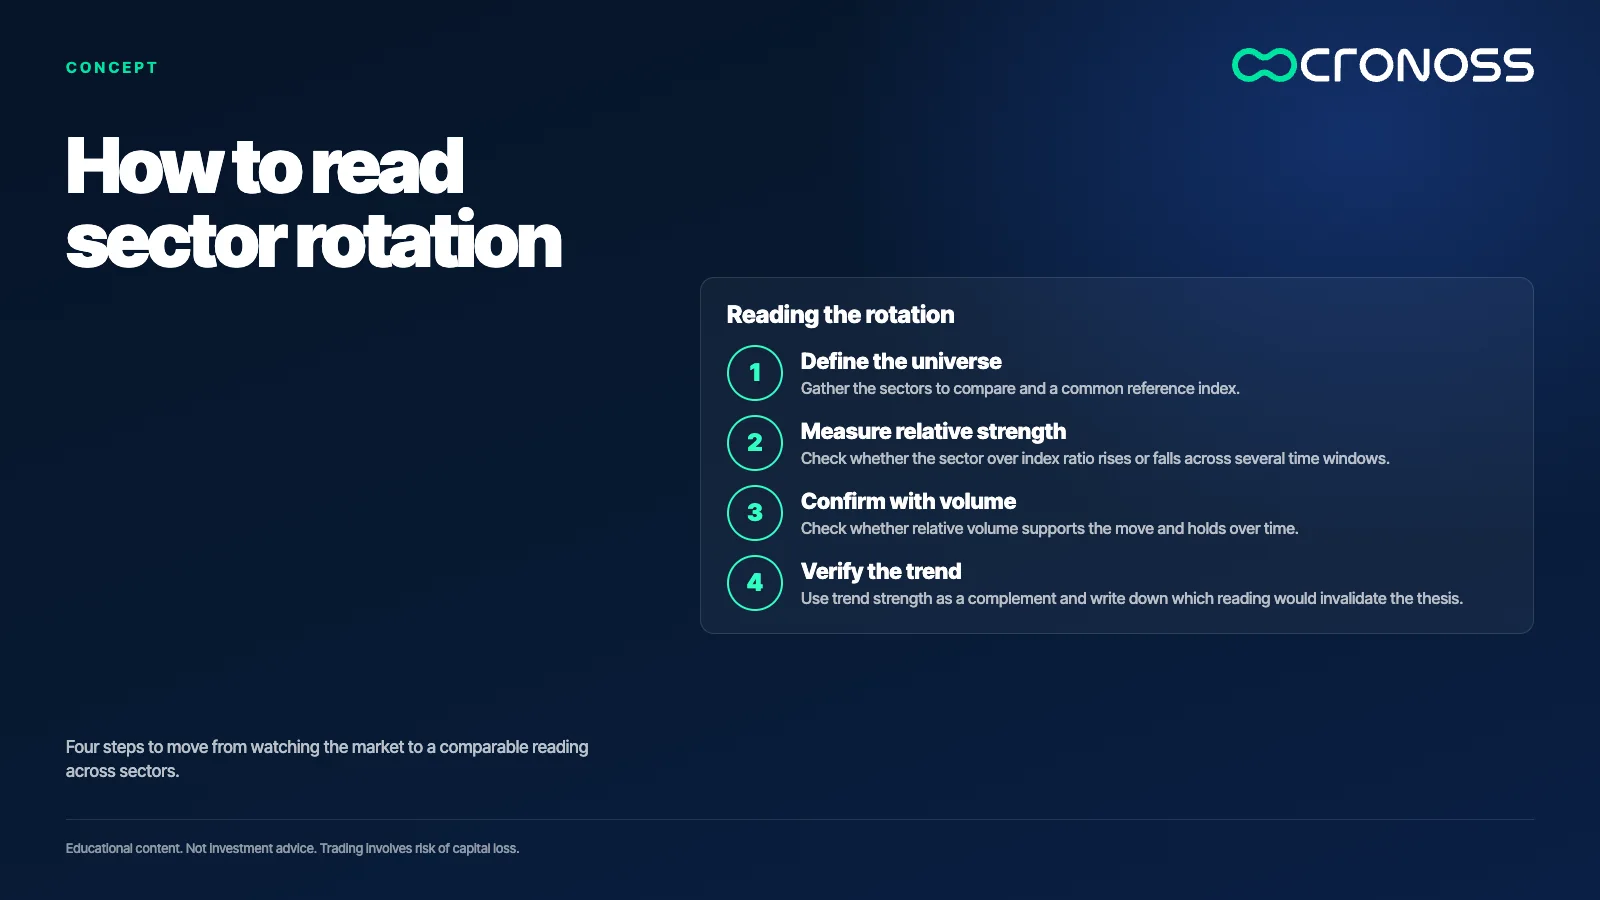
- Compare relative strength of the sector against its reference index over at least three time windows. If it improves in only one, the signal is weak.
- Require volume confirmation. Check whether relative volume stays above its average during the move, not only on a single day.
- Verify trend strength and write down in advance which reading would invalidate your thesis. If that point is unclear, the move is not yet a reading.
Risk: even with all three conditions met, a sector can reverse. If the reading fails, the investment can lose value, so the size of each position must be able to absorb that scenario. This is an analysis method, not an instruction to buy or sell.
Reading rotation is not predicting it
Sector rotation helps describe where the market's strength sits and structures questions about the portfolio. It does not promise to anticipate the next move. Those who use it well ask less which sector will rise and more what evidence they have today, and what would make them change their mind.
Reading where the money is moving helps you decide with more order, not to be right every time.
If you want to go deeper into this reading, review the program Fundamentos de Portafolios de Inversión (Fundamentals of Investment Portfolios) at this link.
Educational content. Cronoss is not a broker, investment firm or financial adviser, and nothing above is an investment recommendation.
Frequently asked questions
What is sector rotation?
It is the tracking of how capital moves between sectors of the economy over time. It is read by comparing each sector's strength against a reference index, not by looking only at whether it rises or falls.
What does relative strength of a sector measure?
It measures whether a sector is beating or trailing the market over a given period. It is calculated by dividing the sector's price by a reference index's price and watching the direction of that ratio.
Why does volume help confirm a trend?
A move backed by growing volume shows there is enough trading to sustain it. A move on thin volume is more likely to reverse, even when the price chart looks good.
What can ADX not tell you?
ADX does not indicate direction, only how strong a trend is, and it is calculated from price, so it arrives after the fact. It works best as a complement rather than as a single signal.


