Key takeaways
- The Turtles experiment tested whether novices could trade real capital by following written rules.
- A method exists if entry, exit, size and loss cut are written without ambiguity and can be executed without improvising.
- Scaling position size to volatility makes risk comparable across different assets.
- A trend-following system can be profitable with few winners if the wins are much larger than the losses.
- The case is a small sample from a specific era: it helps explain process, not reproduce results.
In the early 1980s, two futures traders in Chicago argued over a question that is still open: is profitable trading talent or method? One held that the ability to read the market and manage risk is something you either have or do not. The other believed anyone could learn it if the rules were clear and followed without exceptions.
To settle it, they ran an experiment. They looked for people with no experience, taught them a set of written rules and put them to trade with real capital. That group went down in history as the Turtles, and what it left behind is not a formula for winning but a way of thinking about what having a method means.
A trading method exists only if it can be written in enough detail that another person can execute it without improvising, and that is also what makes it measurable.
The argument that started the experiment
Richard Dennis, a commodities trader, believed his way of trading could be passed on. William Eckhardt, his partner, thought it depended on personal qualities that are hard to teach. Instead of arguing further, they recruited applicants through an advertisement, with one entry condition: no trading knowledge was needed, but candidates had to be willing to follow the rules to the letter.
What the experiment tested was not an indicator. It was the hypothesis that a set of explicit rules, applied with discipline, can replace intuition.
What the rules were made of
The system leaned on the ideas of Richard Donchian, a pioneer of trend following: do not predict where price will go, enter once a trend is confirmed. The entry signal was a breakout of the 20-day high (or low) in a short system, and of the 55-day high (or low) in a long one. The exit came when price broke the low (or high) of the prior 10 or 20 days.
The rules were simple. What made them a system was that they covered the four decisions every trade requires: when to enter, when to exit, how much to risk and where to cut a loss.
Position size was written down too
The original rules scaled the position to the asset's volatility. A hypothetical example: a USD 100,000 account and an asset whose average daily move over the last 20 days is USD 2 per share.
- Unit size: 1% of the account / USD 2 = USD 1,000 / USD 2 = 500 shares.
- Loss if price moves 2 times that average move against you: 500 x USD 4 = USD 2,000, which is 2% of the account.
With this logic, a very volatile asset gets a small position and a calm one gets a larger position, so the risk per asset becomes comparable. It is a way of applying affordable loss at the level of each trade, without depending on the mood of the day.
Why the method matters more than the indicator
A strategy that each trader adjusts depending on the day stops being a strategy. If you enter early because it looks like a good idea, change size because you feel confident or move the exit because closing hurts, there is no way to know what was working: the rule, the mood or luck.
That is the difference between improvising with an idea and having a method. When the rules are applied the same way every time, the result can be measured and deviations are visible. When they change whenever something feels uncomfortable, nothing can be evaluated.
Following a trend instead of predicting it
A breakout system does not try to guess where a move begins. It waits for price to confirm that something is happening and enters afterward, accepting that it misses the first part. In exchange, it does not need to be right most of the time.
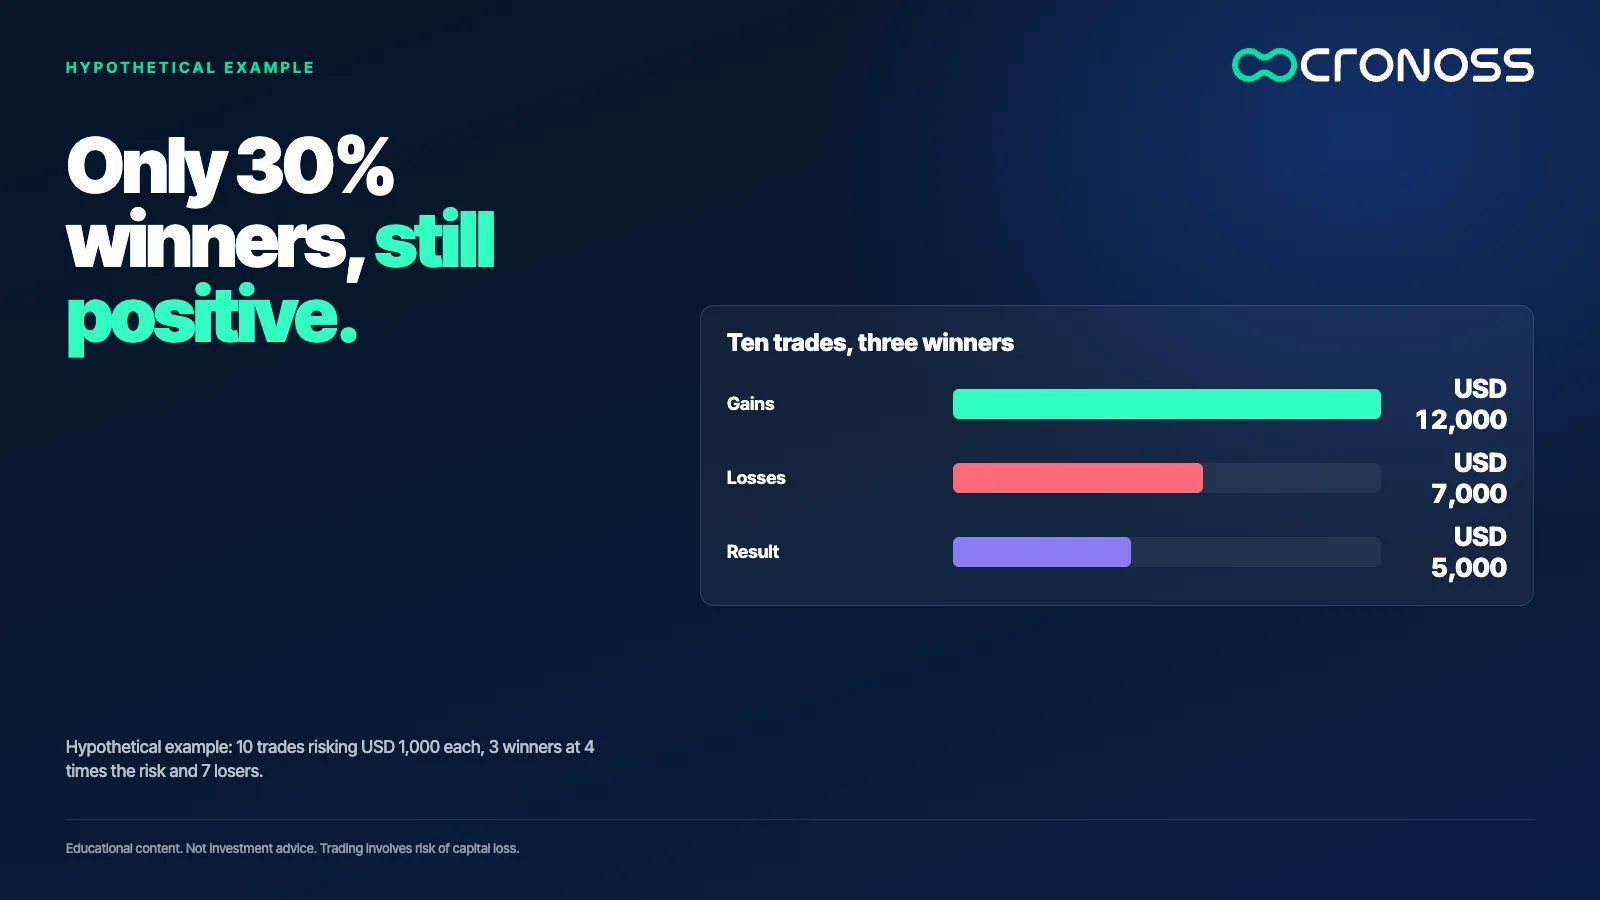
A hypothetical arithmetic example. A system risks USD 1,000 per trade and, when it is right, earns 4 times the risk (USD 4,000). Over 10 trades, 3 winners and 7 losers:
- Gains: 3 x USD 4,000 = USD 12,000.
- Losses: 7 x USD 1,000 = USD 7,000.
- Result: +USD 5,000 even with only a 30% hit rate.
The break-even point is 1 / (1 + 4) = 20% hit rate. It is the flip side of what happens when you lose more than you win on each trade: what matters is the relationship between the size of wins and the size of losses, and that relationship is decided with rules written before trading. The cost is psychological, because most trades lose and the plan has to be sustained through losing streaks.
What the experiment does not prove
This case should be read with care:
- It is a small sample. It involved about two dozen people, selected, in a specific era.
- It happened in futures markets with pronounced trends. Conditions change. A 20-day breakout today coexists with more noise and more participants applying similar ideas, and an edge that many exploit tends to fade.
- Not every participant did equally well. Following the rules demands a discipline that not everyone maintained.
- Past results do not guarantee future results.
The value of the experiment lies in the lesson about process, not in reproducing the rules as they were.
What to check if you want to trade with a method
- Write down the four rules: entry, exit, size and loss cut. If they cannot be written without the phrase "depending on how it looks", there is still discretion.
- Test the rule on data you did not use to design it and measure how much it loses in its worst periods, not just how much it earns.
- Run it unchanged for a number of trades defined in advance and note every time you deviate. Deviations are data too.
A method is not a guarantee
The question of talent versus method has an uncomfortable answer for both sides: a method does not ensure profits, and intuition without rules cannot be evaluated. A method is worth having because it lets you know whether you are wrong and how much being wrong costs.
If you want to learn how to turn an idea into a set of measurable rules and test them, the program Fundamentos del Trading Sistemático (Fundamentals of Systematic Trading) develops that path: see the program.
Educational content. Cronoss is not a broker, investment firm or financial adviser, and nothing above is an investment recommendation.
Frequently asked questions
What was the Turtles experiment?
It was a 1980s experiment in which two futures traders taught a written set of rules to applicants with no experience and put them to trade with real capital. It aimed to answer whether profitable trading can be taught. The group became known as the Turtles.
What is a breakout strategy?
It is a strategy that enters when price exceeds its high (or breaks its low) over a period, for example the last 20 days. It seeks to follow an already confirmed trend rather than predict it. It accepts missing the first part of the move and several false signals.
Can the Turtles rules be used as is today?
There is no guarantee they work today. Markets, participants and noise have changed, and an edge that many exploit tends to fade. Any rule should be tested on your own data and with limited risk before it is applied.
Can you profit with few winning trades?
Yes, if average wins are much larger than average losses. With wins of 4 times the risk, the break-even point is a 20% hit rate. The cost is sustaining long streaks of small losses.